What Happened
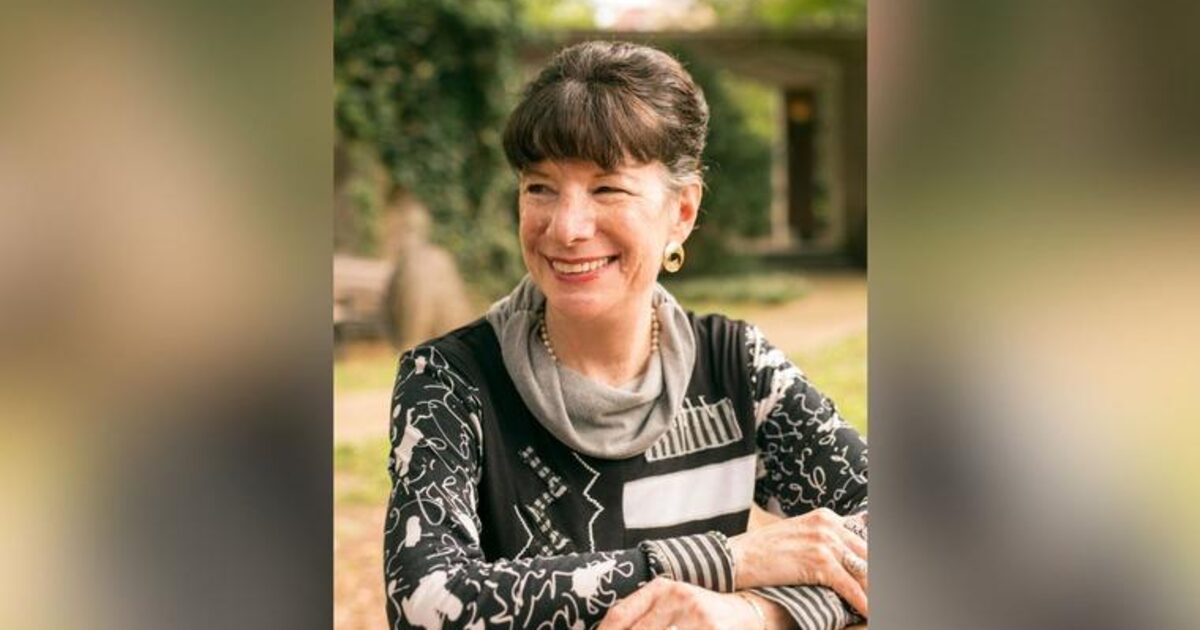
A long-established scholarly association focused on biblical studies reportedly elected a new president for a one-year term at its annual meeting. According to reports, the incoming president is a well-known Jewish scholar of the New Testament — the first non-Catholic to hold the top role at the group, which is described as open to scholars of any faith but has historically been led by Catholics.
The association is a private, member-run organization. It is not operated by any church, but it reportedly provides scholarly consultation to a national bishops' conference, including on Bible translation and religious education materials. The new president has said she plans to focus on educator resources, international participation, and partnerships with local parishes.
While the story is primarily a religious and academic one, it also touches on themes that come up regularly in nonprofit and association law: how a member organization picks its leaders, how its stated mission interacts with its bylaws, and what duties officers generally owe once they are elected.
Why It Matters Legally
Scholarly associations, professional societies, and faith-affiliated groups are usually organized as nonprofit corporations under state law. That means their operations are shaped by three overlapping sets of rules:
- State nonprofit corporation statutes, which set default rules on things like meetings, elections, and recordkeeping.
- The organization's own governing documents — typically articles of incorporation and bylaws — which spell out who counts as a member, how officers are chosen, and what the group's stated purpose is.
- Federal tax law, if the group holds tax-exempt status (often under Section 501(c)(3) for educational, scientific, or religious purposes), which generally requires the entity to stick to its exempt purpose.
Who Could Be Affected
Even though this specific story does not involve a lawsuit, similar governance moments matter for several groups of people:
- Members of associations, who generally have voting rights defined by bylaws and may care about who is eligible to lead.
- Board members and officers, who typically owe fiduciary duties to the organization once elected, including duties of care, loyalty, and obedience to the mission.
- Employees and volunteers of the nonprofit, whose day-to-day work may shift when leadership priorities change.
- Donors and grantmakers, who often rely on the stated mission when deciding to support an organization.
- Partner institutions — such as churches, universities, or government advisory bodies — that receive consultation from the nonprofit and may want to understand any governance shifts.
How Cases Like This Generally Work
When a lawyer is asked to review a nonprofit leadership question — whether it is a routine election, a disputed vote, or a strategic pivot — the analysis usually follows a familiar pattern.
1. Start with the governing documents. Bylaws typically define who can vote, how nominations happen, quorum requirements, term lengths, and any eligibility criteria for officers. If the bylaws do not restrict a role to members of a particular faith or background, then a broader pool of candidates is generally permitted, even if custom has been otherwise.
2. Check the stated mission. Nonprofit articles of incorporation and 501(c)(3) filings describe the organization's purpose. Leadership plans that fall within that purpose are generally uncontroversial. Plans that could be viewed as drifting from the purpose may prompt questions from members, regulators, or the IRS.
3. Consider fiduciary duties. Officers and directors of a nonprofit generally must act in the organization's best interest, avoid conflicts of interest, and steward assets responsibly. Personal views on unrelated matters do not usually change those duties, but leaders are typically expected to keep organizational statements aligned with the entity's mission.
4. Look at outside relationships. If the nonprofit consults for a third party — for example, providing scholarly input to a religious body or a government agency — those relationships are often governed by memoranda of understanding, letters of engagement, or long-standing custom. Lawyers may examine whether those documents anticipate leadership transitions.
5. Watch the timeline. Officer terms, annual meetings, and reporting deadlines are typically set by bylaws and state law. Most state nonprofit statutes require annual reports and can impose consequences for missed filings.
In a disputed election, courts generally defer to the organization's internal rules unless something clearly violated the bylaws or state law. Judges are typically reluctant to second-guess the internal affairs of a religious or expressive association.
What to Watch Next
For a governance story like this one, follow-up coverage might touch on:
- Strategic plan updates, including any new programming, translations, or educator resources the association rolls out.
- Partnership announcements with parishes, dioceses, or interfaith bodies.
- Public statements from the association or its consultation partners clarifying scope of work.
- Any internal challenges from members regarding eligibility or bylaws — these would typically first move through internal grievance procedures.
- Filings with state charity regulators or updated IRS Form 990s, which are public and can reveal governance changes.