What Happened
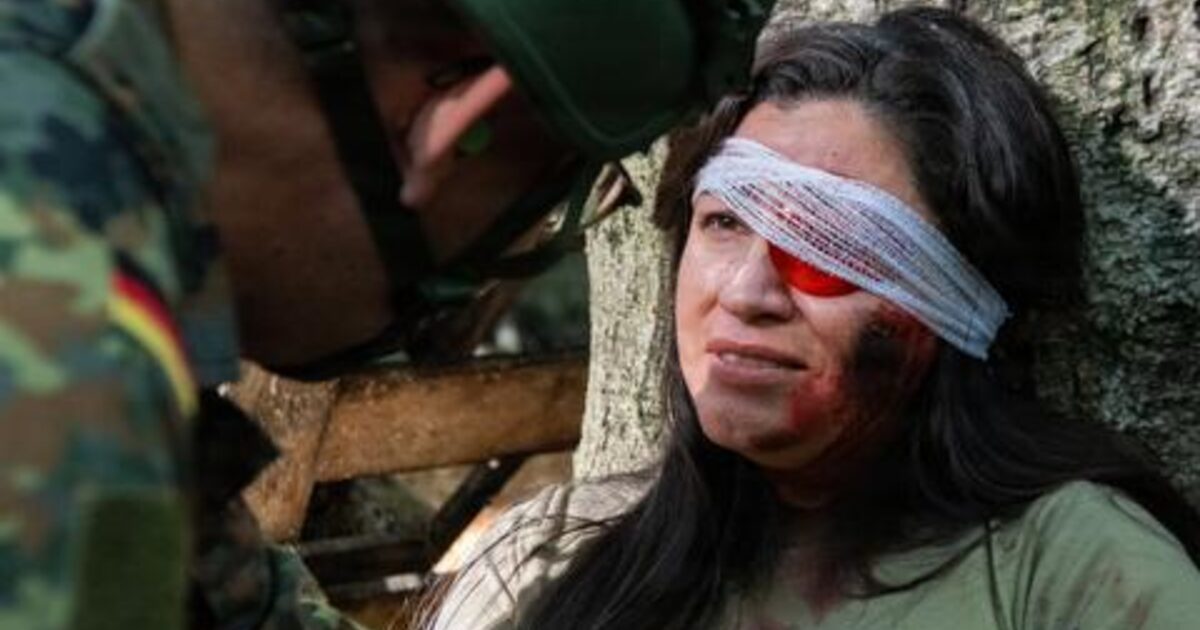
Recent reporting from Germany describes a multinational training exercise near Ramstein Air Base, where U.S. military chaplains reportedly worked alongside counterparts from nearly a dozen NATO allies and partner nations. Over three days, participants reportedly practiced what they called "foxhole ministry" — ministering to simulated wounded troops of different faiths, taking cover from mock drone strikes, and rehearsing dignified transfers and battlefield memorials while explosions played in the background.
The exercise, reportedly sponsored by U.S. European Command, was described as the third iteration of the program. According to the reporting, it reflects a broader NATO effort to prepare for large-scale combat as the war in Ukraine continues and concerns about a wider European conflict persist. Participating nations reportedly included the United States, Germany, the Netherlands, Belgium, Finland, Denmark, Romania, the Czech Republic, Slovakia, and Kosovo.
On its face, this is a military readiness story. But behind every deployment order is a stack of legal and financial rules that quietly kick in for the service member and their family — including some of the most significant tax-relief provisions in the federal code.
Why It Matters Legally
When U.S. troops train for and eventually deploy to a hazardous overseas assignment, federal tax law generally stops treating them the same as civilian filers. Congress has long carved out special rules for service members serving in combat zones or designated hazardous duty areas. These rules can reduce taxable income, push back filing deadlines, pause certain IRS collection activity, and protect state residency status.
Lawyers, enrolled agents, and CPAs who work with military families pay close attention to stories like this because a growing NATO footprint in Europe could mean more deployments, more temporary duty assignments, and more families trying to sort out which benefits apply to which paycheck and which tax year. Getting it wrong can lead to overpayment, missed refunds, or unnecessary IRS notices; getting it right generally requires understanding both the federal exclusions and the patchwork of state rules.
Who Could Be Affected
Several groups may have tax-relief questions after news like this:
- Active-duty service members deployed to a designated combat zone or contingency operation area.
- Reservists and National Guard members called up on federal orders for overseas duty.
- Support personnel such as chaplains, medics, linguists, and logistics staff assigned to a qualifying zone — their duties do not need to involve direct combat.
- Military spouses and families back home, who may be managing joint returns, estimated payments, and state residency questions while their partner is deployed.
- Veterans who separated recently and are only now dealing with tax issues from a prior deployment year.
How Cases Like This Generally Work
A tax professional reviewing a deployed service member's situation would generally start with a few core questions.
Is the duty station in a recognized combat zone or qualified hazardous duty area? The IRS maintains a list of these areas, which the President designates by executive order and Congress can add to by statute. Certain support locations tied to a combat operation may also qualify. If the answer is yes, a large portion of enlisted pay — and capped portions of officer pay — may generally be excluded from federal gross income under Internal Revenue Code Section 112.
What are the deployment dates? Under Section 7508, the IRS generally extends filing, payment, and many other deadlines for service members in a combat zone. The extension is typically 180 days after the last day in the zone, plus any days that were left in the normal filing window when the deployment began. During that period, the IRS generally does not assess interest or late-filing penalties on covered obligations, and certain collection actions are generally paused.
What about state taxes? The federal Servicemembers Civil Relief Act (SCRA) and the Military Spouses Residency Relief Act (MSRRA) generally allow service members and many spouses to keep their home-of-record state for tax purposes, even when stationed elsewhere. That matters a great deal in high-tax states versus no-income-tax states — the difference between, say, keeping Wyoming residency while stationed in Virginia can be significant. Rules vary state by state, so a return filer would typically look at both the home state's military guidance and any state where wages were earned.
What evidence matters? Practitioners generally want to see deployment orders, LES (Leave and Earnings Statements) showing combat zone tax exclusion codes, travel vouchers, and any correspondence from the IRS. Clean documentation is generally the fastest way to resolve an IRS notice that questions why a return was filed late or why income was excluded.
What if a notice already arrived? For service members who received an IRS notice during or shortly after a deployment, tax-relief options may include requesting abatement of penalties, invoking combat-zone protections retroactively, or entering into installment agreements or offers in compromise once the facts are documented.
What to Watch Next
Readers following this story may want to watch for a few developments in coming months:
- New or expanded combat zone designations. If NATO tensions escalate, the executive branch could add locations to the list, which would generally change tax treatment for troops stationed there.
- IRS guidance. The IRS periodically updates Publication 3, the Armed Forces' Tax Guide, and issues notices clarifying how deployment-related benefits apply to specific operations.
- State legislation. States including Colorado, Virginia, Wyoming, Pennsylvania, and Kansas have their own military tax rules, and legislatures sometimes expand exemptions for retirement pay, combat pay, or spouse income.
- Court rulings and administrative decisions on how MSRRA applies to remote-working spouses, which has become a growing question as more military families work across state lines.